Published by Jeremy. Last Updated on August 7, 2026.
Disclaimers: Our site uses demographic data, email opt-ins, display advertising, and affiliate links. Please check out our Terms and Conditions for more information. Listed prices and attraction details may have changed since our visit and initial publication.
When we tell people we sometimes travel the world for free, they often look at is with a bit of incredulity.
Those who know us instantly assume it is because of this travel blog and that we bounce around from press trip to press trip. But we often shock them when we say that is not our scene and we go on few, if any, hosted trips. In fact, when we travel we don’t even pitch brands to work with.
It is something that we never enjoyed doing, so we don’t do it.
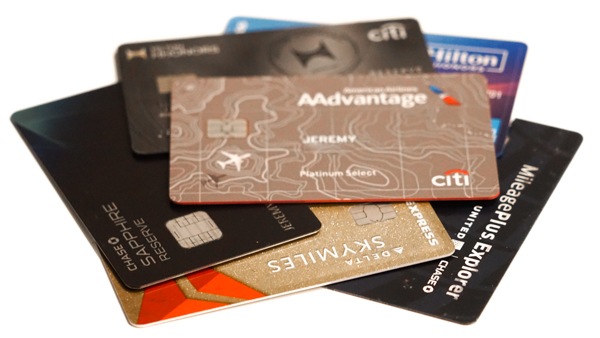
Our travels are instead often paid through points which we acquire in a mix of paying for travel with large companies and travel credit cards. So in this one, we thought we’d share about how our travel credit cards have helped us earn a ton of free (and deeply discounted) travel!
All cards featured herein are cards we personally have in our wallets right now (both of us in most cases- double the rewards!), and we will do our best to update this guide as we open or close cards in the future.
📍 The Best Travel Credit Cards – A Quick Look
- Specific to You: Many popular global travel brands have affiliated credit cards with wonderful perks and sign-up bonuses- often the best cards those that are aligned with brands you use regularly over those you may only use periodically
- Minimum Spends: Travel credit cards often have limited time promotions at signup to get massive points and/or reward stays for hitting a minimum spend, typically $3,000 to $6,000 in anywhere from three to six months- meeting these yields excellent returns
- Don’t Needlessly Overspend: Going out of your way to spend more (for minimum spends), or not getting enough tangential perks to justify annual fees, can make opening credit cards not worth it in the long run- only open cards that fit with your current spending habits
A Few Upfront Disclaimers
Before getting into it, a few disclaimers are necessary.
We were not requested to publish this article in any capacity. Some links within this post do contain referral codes, however. If you sign-up for a credit card via our links we may receive additional points into our accounts.
In addition, please note that sign-up perks, requirements, and fees are based on the offering at the time of publication and are prone to change without notice. We will update this post from time to time to reflect any changes, but we cannot guarantee that what you see below will be what is available when you click.
Finally, please review all T&Cs before signing up for a card. If you spot a discrepancy from anything posted below, please contact us and we will update this post accordingly.
Alright, now that those are out of the way lets get to the cards that we currently use to gather up points to travel with!
Chase Sapphire Preferred
Sign-Up Bonus: Generally 75,000 points after spending $5,000 in 3 months
Other Perks: Global entry credit, $100 Chase Ultimate Rewards hotel credit per year, 2x on travel (5x if using the Chase portal for flights and hotels), 3x on Airbnb, 3x on select dining, 3x on groceries, 3x on streaming, 3x on gas, and select partner promotions
Annual Fee: $95 annual fee
For many years, my wife and I both held the premium Chase Sapphire Reserve card for its higher rewards points and getting a Priority Pass; however, after that one increased its fee to $795/year, we downgraded one of our cards to the Preferred at a much more reasonable $95/year. (We still keep one Reserve for Priority Pass, StubHub Credit, slightly higher points, and more- but you need to be careful that you can get the price difference in returned value- we may downgrade the second card soon ourselves.)
Although other cards in this list have better rewards, particularly for specific hotels or airlines, a general Chase card is great for two reasons.
First, you can transfer points to numerous partner networks. So instead of being locked into building points on, say, United, you can be flexible on transferring points to partnered alliances when you want to redeem.
Second, Chase has its own travel portal for booking with points redemption bonuses as well. So if there is a flight or hotel deal where the overall cost is low but the branded points redemption on the associated network is high, booking directly through Chase has had its perks (loss of status and no points for 3rd party bookings notwithstanding).
Still, as we are often quite flexible on where we travel, and sometimes send the Chase points off platform directly to a partner network (say, United), it is nice to have something like this card for flexibility when we don’t know what kind of reward we want to redeem.
Will we keep the card? Admittedly, one of the biggest reasons we have kept this card is simply because we’ve had it opened for so long and our credit history is high because of it. But being flexible as noted above is one reason why we are likely to keep this card and its nominal fee moving forward- our everyday spending lets us get a free plane ticket anywhere in the world, sometimes even in business class (one way) every year or so.
Thinking of grabbing this card? Click here to sign up for the Chase Sapphire Preferred card.
Chase United Quest
Sign-Up Bonus: Typically 60,000 points plus 500 PQPs after spending $4,000 in 3 months
Other Perks: Two free checked bags on United, Priority Boarding, 6x to 10x miles on United per dollar spent, 10% off rewards bookings, a 10,000-mile annual reward flight discount, $200 in United travel credit, and other credits as well.
Annual Fee: $350 annual fee.
For many years, I had United’s $95 credit card, the United MileagePlus Explorer. It was my first travel credit card and one of the longest I’ve had opened such that I was almost keeping it open for my credit history as much as I was any travel benefit. But around 2021, I upgraded this card to a new premium tier, the United Quest, that comes in at a $350 annual price point.
The reason I upgraded this card is simple- Angie could no longer maintain status on United every year, and without that we were back to having to pay checked bag fees when we travel. The Quest card is unique in that you and a companion both get checked bags on your United flight insofar as the flight is booked with the credit card.
For us, that was worth the extra $255 a year several times over as bag fees, especially second bag fees, can add up in a hurry.
Beyond this, the credit card boasts most conventional perks that you would expect- upwards of 10x on United, 2x on other travel, 2x on dining, plus $200 in United statement credit annually, discounted reward flight options, and priority boarding.
The only thing this card does not have that the $95 card does is 2x annual United lounge passes; however, we never found United lounges to be that great anyway, so we’d rather have the checked bags and statement credit.
Will we keep the card? We have no intention of canceling this card as long as the checked bags are included. We fly with United as our primary carrier often enough to make this one worth it for the bags and $200 annual credit alone. That said, it is worth keeping in mind that flights must be booked with this card to receive the bag perks and admittedly that is something we have forgotten from time to time. So while we make most of our everyday purchases with our Chase Reserve, any United bookings go straight through this card for the extra benefits!
Thinking of grabbing this card? Click here to sign up for the United Quest card.
Delta Skymiles Gold
Sign-Up Bonus: 60,000 miles after $4,000 spent in six months
Other Perks: 2x points on Delta, 2x on other USA spending like restaurants, 15% off award travel, free checked bag (two on domestic), $200 delta flight credit after $10,000 in spending, monthly rideshare credit, Delta stays credit, and zone 5 boarding
Annual Fee: $0 first year then $150
Delta has a great rewards card on American Express that has many of the perks of the United Quest card, albeit perhaps for a little less in annual fees.
Admittedly, I signed up for this card purely for an easily attainable sign-up bonus as the spending period is often a fair bit longer than other cards. Throw on 15% of award travel booking and it was very easy for us to get a free round trip ticket to Europe here after a few more months of using the card regularly.
Will we keep this card? Admittedly, probably not, if only because we do not fly Delta regularly the way we do on United. Throw on that the annual credits are only after a minimum spend and the second free bag is only on domestic flights, and there are a few slight drawbacks to this card compared to the United card (which, admittedly, is more expensive) that come together to make this a one-and-done card for us most likely. Still, thanks for the free trip to Europe!
Thinking of grabbing this card? Click here to sign up for the Delta Skymiles Gold card
Chase Marriott Bonvoy Boundless
Sign-Up Bonus: Typically 4 Free Night Awards (up to 50k points per) after spending $3,000 in 3 months.
Other Perks: Upwards of 17x per $1 spent at Marriott properties, 3x on groceries and gas up to a certain limit, 2x per $1 on most other spending. Free night on anniversary up to 35,000 points. 15 night credit on account to higher status (instant silver status). An extra elite night credit for every $5,000 spent.
Annual Fee: $95 annual fee
On its own, I’d say that the Chase Marriott Bonvoy Boundless card is only a decent hotel card. The anniversary night more or less covers the annual fee (and then some) and the multiplier, plus 15 night stay credit towards status, makes this a solid card for Marriott loyalists.
For me, I actually have this plus the business Marriott card on American Express which has very similar bonuses and perks as well (more on that below). But why have two when they both have the same perks? Well, with Marriott cards you can double up the elite night credits to get closer to a higher status- something that is a bit unique amongst hotel cards.
With one card, the 15 night credit will get you automatic silver status, and with a second card an additional 15 nights will get you into gold (25 night threshold). From there, it is just 20 more nights to get to platinum status which is where some really fun perks come into play (think suite upgrades, lounge access, etc). 50 nights is a bit of a stretch for us, but 20 a year is doable and most certainly worth targeting to get that upgraded status.
The only downside is that the 35,000 annual free night credits only open up some of the more bare-bones properties out there; however, cardholders can apply some points to book higher-tier properties (with a cap). So if you want to dip a bit into your points stash, these certificates aren’t too bad.
Will we keep the card? My two Marriott cards are primarily used as a means to reach platinum status easier and then reaping the rewards of upgraded stays when we travel. As the free night certificates on both cards more or less cover the annual fee, we see no reason why we’d get rid of these cards any time soon. That said, since we do not hit platinum every year, we’re mostly holding onto these until we at least get to lifetime gold status, and then we may change plans.
Thinking of grabbing this card? Click here to sign up for the Chase Marriott Bonvoy Boundless card.
American Express Marriott Bonvoy Business
Sign-Up Bonus: Upwards of 125,000 Bonvoy points with a minimum spend (ranges but tends to be higher than personal cards)
Other Perks: Gold status, 7% discount on Marriott stays, 6x per $1 spent at Marriott properties, 4x at restaurants/US gas stations/phone fees, 2x per $1 on other spending. Free night on anniversary up to 35,000 points. 15 night credit on account to higher status.
Annual Fee: $125 annual fee
American Express also offers a Marriott card, but only for business consumers. This one is slightly more expensive, $30/year more than the personal card, but comes with more perks particularly in the form of automatic gold status, a slight discount on stays, and another free night certificated worth 35,000 points that more than covers the annual fee.
Objectively, this is a slightly better card than the Chase personal one simply because you automatically get gold status without needing to hit the minimum qualifying nights. But since this card also offers 15 elite night credits per year, this is a good one to combo up with if you are trying to get into higher award tiers or lifetime status.
So while you wouldn’t necessarily need both cards if you wanted to stop at gold status and don’t care about reaching lifetime, there are still good arguments for having both- namely two reward certificates each year.
Will we keep the card? As mentioned with my other card, this combination is purely a play for lifetime status at higher tiers with the 30 combined night credits annually. That said, if the program ever changed to make it harder to reach higher status and this card still kept automatic gold, we would likely keep this one and ditch our personal. But for now, let’s rack up those nights!
Thinking of grabbing this card? Click here to sign up for the Chase Marriott Bonvoy Boundless card for businesses.
A Few Notes About Opening Credit Cards
When it comes down to it, we love opening and using credit cards to help us out in accumulating a massive amount of points to travel the world for free (or close to it).
But we have to provide a word of caution in say that just because we can open several cards and keep them open, that does not mean it is the best course of action for everyone.
The reasons for this are simple, and boil down to the fact that we can simply afford the fees (and in most cases get enough perks out of the card that vastly outweigh said fees such that our spending actually goes down), can easily meet the minimum spending requirements, we never pay interest, and even when factoring in all of that still come out ahead over simply paying for our trips outright.
We cannot tell you if that would be the same for your situation.
This is why we had a bit of a discussion on whether or not we would keep each card in the long-term. As you can tell from the above discussion, some cards are great and we will hold onto as long as the terms don’t change, whereas others we are only holding for a brief period of time while the perks work for us. We analyze this yearly, and ditch cards that end up costing us more than the value we receive regularly.
You would be wise to do the same.
As such, if you are looking at opening credit cards for their sign up rewards we urge you to strongly look at your financial situation and see if it is practical.
If it isn’t, many of the above companies offer free cards that have no annual fee but still provide some rewards upon opening or meeting a lower minimum spending limit (typically $1,000 to $2,000). We started with these and as our income and spending grew, we upgraded. As far as maintaining good credit, there is no shame in going slow.
Read More Lifestyle Design Articles
About Jeremy
About the Author: Jeremy is a full-time travel writer based in Pittsburgh and primary author of this site. He has been to 80+ countries on five continents and seeks out new food, adventure activities, and off-the-beaten-path experiences wherever he travels.
Wow! Thank you for giving a great rundown on each card that YOU have actually used! I think you also do a good job conveying to use them responsively.
Thanks! We hope to keep this one a running guide to give a snapshot of cards we personally use. (And perhaps a backlog of ones we previously had as well.) Certainly helps us convey our goal of racking up points more!